All Categories
Featured

Comparing PPO and HMO Health Plans
Table of Contents
Like all health plans, receiving in-network care is best to keep your out-of-pocket expenses low. Nevertheless, unlike HMO plans that won't cover any part of your expense if you look for out-of-network care (except in a covered emergency), you can get out-of-network care when taking a trip out of your regular strategy network area with a PPO policy.
Insurance in Indio CACost-conscious people must think about a few downsides to PPO prepares that might make getting care more pricey. While they're versatile and convenient, PPO plans have higher premiums. According to KFF, PPO plans had the highest annual premiums compared to HMOs and point-of-service plans (POS) in 2023. You'll also need to pay more expensive medical costs if you get care from an out-of-network supplier.
If you do have a deductible, it's likely to be more pricey than other strategy types. While your insurance provider will share the expense with you, you'll likely pay a greater coinsurance percentage for out-of-network providers. When you visit an in-network service provider, they'll file your claim to your medical insurance business on your behalf.
PPO policyholders might find the claim filing procedure complicated if they're not used to it or lengthy if they regularly need out-of-network care from a specialist. In 2023, the typical annual premium for a group PPO strategy was $8,906 for self-only coverage and $25,228 for family coverage2. Employers contributed $7,399 toward a self-only strategy, and workers contributed $1,507.
Evaluating Best Medicare Supplement Policies
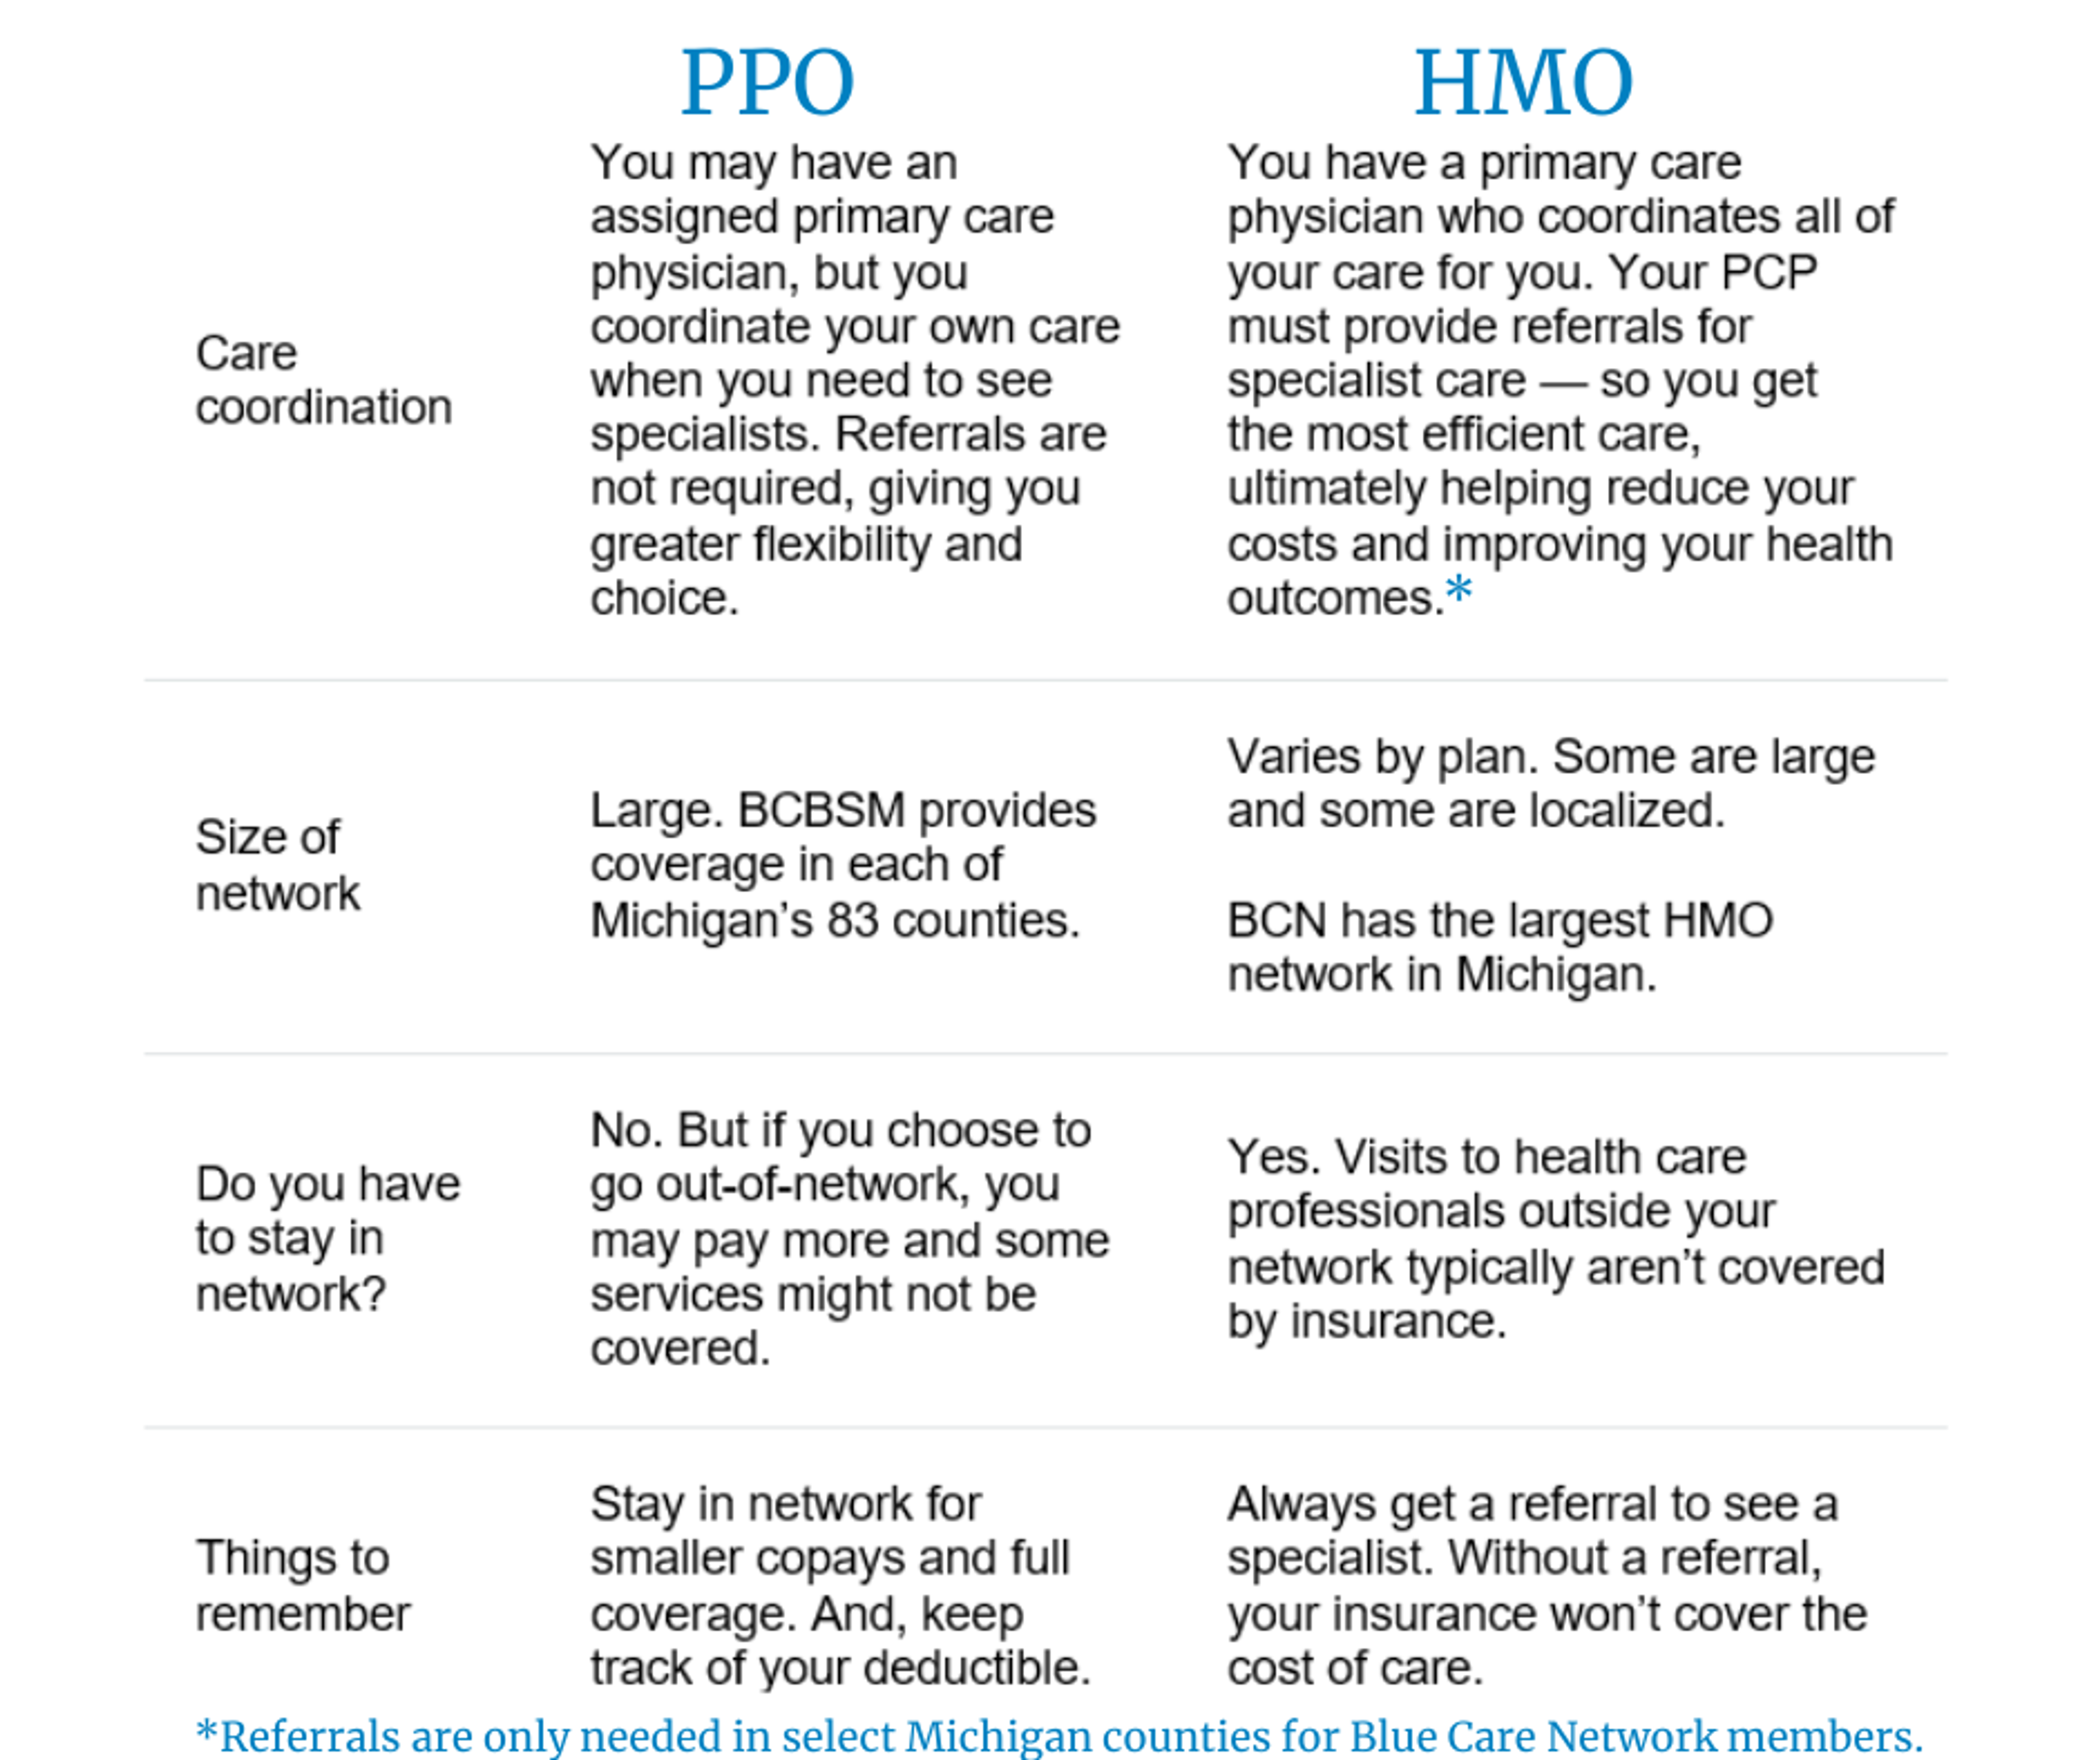
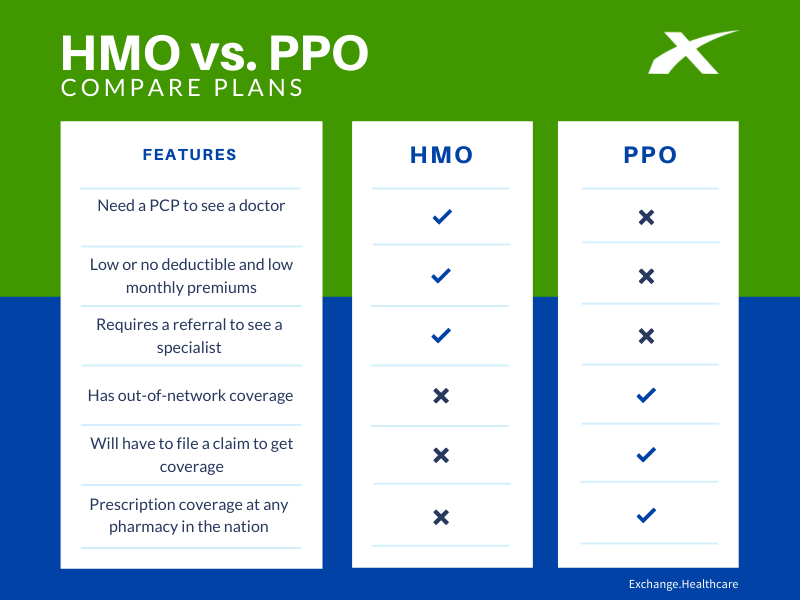
The average deductible for PPO strategies was $1,281. As pointed out above, PPO plans purchased on the ACA markets also have an optimum out-of-pocket limitation of $9,450 for self-only protection and $18,900 for family strategies. To sum up how HMO and PPO plans vary, check out our quick chart. Self-only coverage: $8,203 Family protection: $23,758 Self-only protection: $8,906 Household coverage: $25,228 For 2024 ACA marketplace strategies, the maximum limitation is $9,450 for self-only coverage and $18,900 for household coverage.
Yes No Yes No Some plans do. A lot of plans do. Whether you have an HMO or PPO plan, you can leverage a health reimbursement arrangement (HRA) to lower out-of-pocket medical costs.
Only employers can release and contribute toward an HRA. Employers utilize an HRA to give their workers a monthly allowance to pay for medical expenses. Once an employee purchases a qualified item or service, they submit documentation revealing proof of purchase, and their employer compensates them approximately their allowance quantity.
Reviewing Best Medicare Supplement Policies
Staff member compensations will be tax-free if their individual health insurance uses minimum vital coverage (MEC). Companies can repay staff members for out-of-pocket costs and health insurance coverage premiums, including those for an HMO or PPO strategy. Private protection HRA (ICHRA): An ICHRA is likewise a stand-alone HRA, but it's available to companies of all sizes and has no contribution limits.

However, they need to have a qualifying kind of specific health coverage to participate. Employers can set various allowances based upon worker classes for included modification. Group coverage HRA (GCHRA): Also called an integrated HRA, a GCHRA is for companies of any size who use a group health strategy. Just staff members enrolled in their employer's group strategy can take part.
While they have no optimum contribution limitations, the IRS does not allow compensations for month-to-month premiums. No matter whether it's utilized in coordination with an HMO or PPO strategy, there's an HRA that can help employees spend for their out-of-pocket medical expenses and, sometimes, their health insurance premiums. An HRA is a popular alternative option over conventional health benefits because they're economical for employers and versatile enough for every single staff member.
Maximizing Indexed Universal Life Policy Benefits in Retirement
An HMO may be your best choice if you're searching for a plan with a low premium. Nevertheless, a PPO strategy supplies extra flexibility if you require more control over your healthcare. That's why looking into these plans thoroughly, including their pros, cons, and average expenses, is the best very first action you can take in the past deciding.
(MEC). (ICHRA): An ICHRA is likewise a stand-alone HRA, however it's readily available to employers of all sizes and has no contribution limits.
They should have a certifying type of individual health protection to take part. (GCHRA): Likewise known as an incorporated HRA, a GCHRA is for companies of any size who provide a group health plan. Just staff members enrolled in their employer's group plan can get involved.
Analyzing PPO Network Access and Monthly Costs
While they have no optimum contribution limits, the IRS doesn't permit compensations for monthly premiums. No matter whether it's used in coordination with an HMO or PPO strategy, there's an HRA that can help workers spend for their out-of-pocket medical expenses and, in some cases, their health insurance premiums. An HRA is a popular alternative option over traditional health advantages since they're budget-friendly for employers and flexible enough for every single worker.
An HMO might be your best choice if you're searching for a strategy with a low premium. However, a PPO strategy supplies extra versatility if you need more control over your healthcare. That's why looking into these plans carefully, including their pros, cons, and typical costs, is the finest initial step you can take before making a choice.

Latest Posts
Strategic Financial Security with Modern Life Insurance

Securing Cheap 2026 Family Health Insurance
Expert Consumer Advice for Buying 2026 Insurance